VIX Crashed 44% in 4 Days: What the Fear Gauge Is Really Saying
Between an Iran war, a hot CPI print, and a Fed about to go full hawk, markets are suspiciously calm, and that's the story
Ticker Ratings
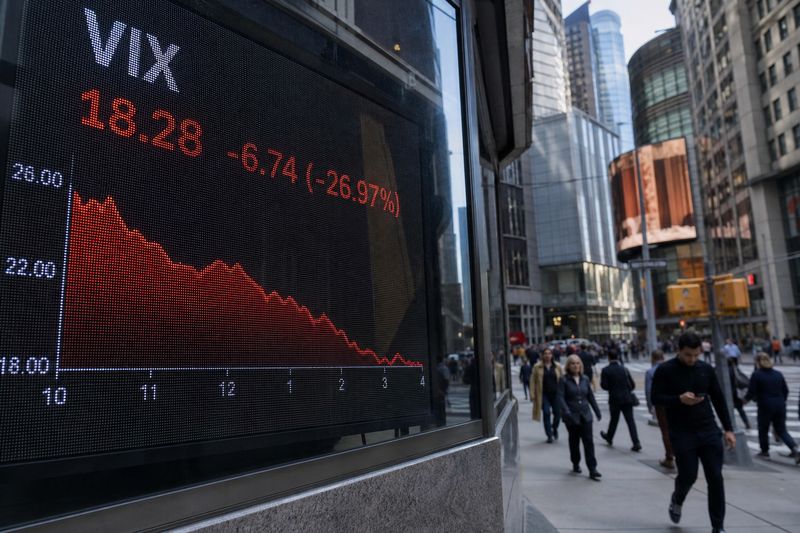
Last Thursday, the VIX exploded +69.66% in a single session, hitting 28.18. By Monday it was back at 19.92, a 22.31% single-day plunge. If you blinked, you missed a full-on panic and an equally confident all-clear. That's not normal market behavior. That's the financial equivalent of screaming fire in a theater and then immediately going back to your popcorn.
Here's what set the stage. The S&P 500 dropped 4.36% on November 5th, the Nasdaq fell 5.52%, and the Dow shed 3.44% in a single day. The culprits were a trifecta of bad news: October CPI came in +0.4% month-over-month, hotter than expected for the third consecutive month, with year-over-year inflation now estimated around 3.8-4%. The 10-year Treasury briefly punched through 5%. And Fed Governor Waller started whispering sweet nothings about a possible 50 basis point hike in December, with Deutsche Bank now calling for three consecutive hikes totaling 75 basis points through March.
Then Monday happened, and everyone seemingly decided the Iran war, the hot CPI, and the hawkish Fed were... fine actually? The S&P 500 bounced 2.35% and the VIX cratered. Here's the uncomfortable read: the market isn't pricing in resolved risks. It's pricing in contained risks, which is a very different thing. Trump dialing back Iran strike talk gave traders permission to exhale, but missiles are still hitting Qeshm Island, shipping attacks in the Strait of Hormuz are ongoing, and US Treasury Secretary Bessent is reportedly at a military base because of Iranian threats. The word "contained" is doing a lot of heavy lifting right now.
Meanwhile, the rotation under the surface is screaming louder than the index moves. Info tech was the worst S&P sector on November 10th, down 1.4%, while financials gained roughly 0.5%. Healthcare names are quietly dominating leadership lists, with traders on YouTube like Investor's Business Daily's David Ryan pointing out that 7 to 8 of the top 11 market groups have "medical" in the name. When the generals fall (looking at you, $NVDA, down 30% from October highs) and healthcare drafts up quietly, that's a rotation worth taking seriously.
Jim Cramer on CNBC made the bull case that a Middle East resolution could send oil to $40 per barrel, which would cascade into genuine inflation relief and flip the entire macro narrative. It's a real scenario. It's also predicated on a geopolitical outcome that feels optimistic when missiles are still in the air. The bear case is simpler: three rate hikes, 5% yields, and an AI sector suddenly missing its most important narrator. The market's calm face might just be the calm before it figures out which story is true.
The VIX at 19.92 isn't panic, but it isn't complacency either. It's the market squinting at the horizon, hoping the thing it sees isn't what it thinks it is.
BullApe's AI grades every pick against the S&P 500 - wins and misses published. See the track record →