AVAV Beats Q1 Estimates and Lands $465M Army Contract
Retail sentiment is quietly rotating into defense names as oil tops $100 and geopolitical risk stays elevated
Ticker Ratings
| Ticker | Rating | Entry Price | Current | $ Gain | % Gain |
|---|---|---|---|---|---|
| AVAV AeroVironment Inc | buy | $147.00 | - | - | - |
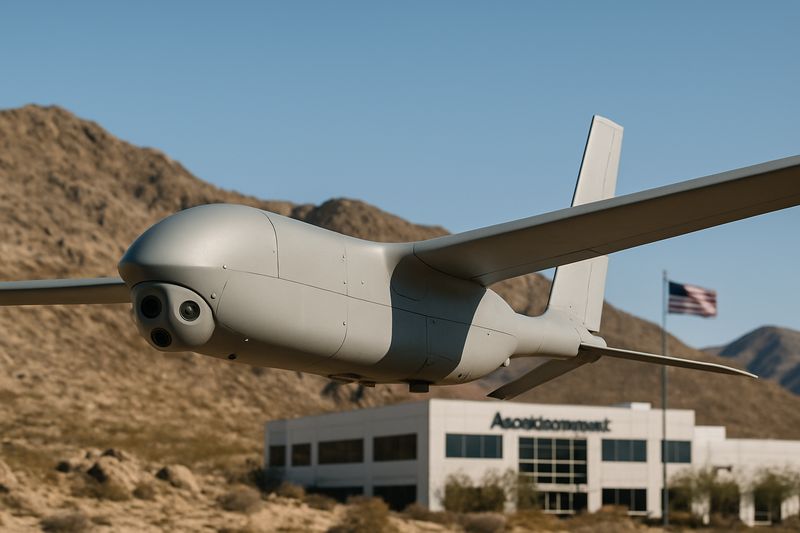
If you spent this week doom-scrolling Hormuz shipping data and Apple foldable takes, you might have missed the one earnings story that actually makes sense in the current macro environment. $AVAV (AeroVironment) posted Q1 revenue above analyst estimates, maintained its full-year 2027 guidance, and announced a $465 million US Army contract for its Locus laser systems. The stock gained roughly 2-4% in after-hours trading. Not flashy. But in a week where the Dow dropped over 1,000 points cumulatively, not flashy is its own kind of beautiful.
The timing here is almost too on the nose. US-Iran conflict is dominating headlines, Hormuz traffic is in single digits, and the VIX is creeping up to 15.72. When geopolitical risk spikes, defense spending narratives get repriced fast. The Locus contract is described as the first of its kind in the defense sector, which matters for forward revenue visibility. AVAV maintained guidance, which in this environment is basically the equivalent of showing up to a house fire with snacks. Calm. Appreciated.
The bull case here writes itself: escalating conflict, a US government doubling down on weapons procurement, and a company that just proved it can beat on the top line. The bear case is also real. Defense stocks tend to front-run the actual spending, meaning the easy money may already be in the price. And if Trump's stated timeline of ending the Iran war after midterms holds, that geopolitical premium could evaporate quickly.
What's interesting from a social sentiment angle is how late retail is to this trade. Bloomberg Podcasts covered the AVAV print almost as an afterthought, buried after the Apple foldable news. YouTube financial commentary has been fixated on oil, crypto, and grocery prices. The defense earnings angle is genuinely undertracked right now, which is either a gift or a trap depending on your conviction.
Meanwhile, $AB Foods is out here cutting profit guidance on its sugar and grocery divisions, citing higher energy costs (hi, $100 oil), and watching Primark sales disappoint heading into Q4. Management is also pivoting to home delivery after years of resisting e-commerce, which is the kind of move that tends to cost more money than it makes in year one. AB Foods earnings are basically the photo negative of AVAV: a consumer brand getting squeezed by the exact macro forces that are padding a defense contractor's order book.
When the best earnings story of the week is a drone and laser company, the market is trying to tell you something.
BullApe's AI grades every pick against the S&P 500 - wins and misses published. See the track record →
Mentioned: $AVAV