ASML's eScan 2200: The $75M Bankruptcy Bet That Could Change Chipmaking
Asianometry breaks down how Mapper Lithography's electron beam tech went from bankruptcy court to ASML's hottest new product
Ticker Ratings
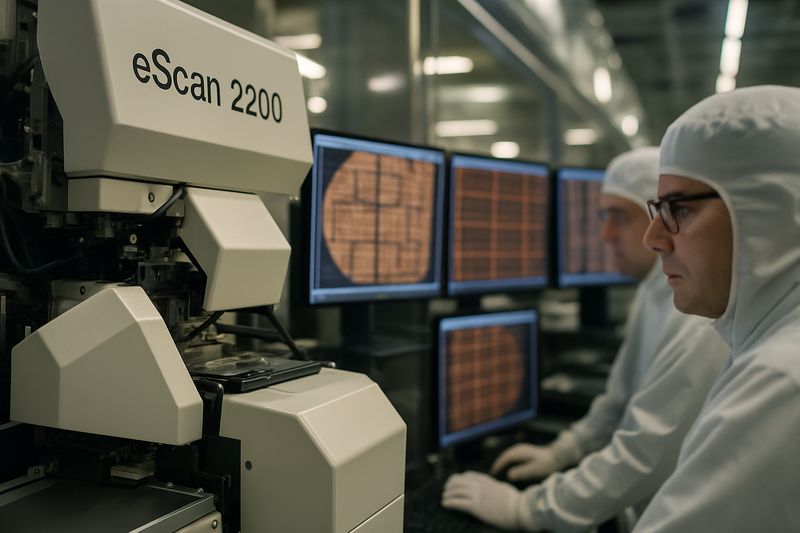
$ASML has a new multibeam inspection tool, the eScan 2200, and its origin story reads less like a product launch and more like a phoenix-from-the-ashes tale with a Dutch accent. The Asianometry YouTube channel just dropped a deep dive explaining how this thing actually came to be, and spoiler: it started with a bankruptcy, a 75 million euro acquisition, and technology that was supposed to replace EUV entirely.
The backstory involves Mapper Lithography, a Dutch startup that spent years developing massively parallel electron beam direct write lithography, or EBDW. The core innovation was splitting a single electron beam into thousands of beamlets, which solved the brutal throughput problem that made single-beam EBDW a non-starter for high-volume chip manufacturing. TSMC was so intrigued it invested in Mapper back in 2008, treating it as a hedge against EUV uncertainty. That tells you everything about how seriously the industry took the underlying technology, even if the company itself didn't survive.
Mapper went bankrupt anyway. ASML swooped in and picked up the pieces for 75 million euros in 2019, which in hindsight looks like one of the better bargain-bin purchases in semiconductor history. The multibeam architecture that Mapper pioneered now sits at the heart of the eScan 2200, repurposed from direct-write lithography into inspection. Different application, same brilliant core idea.
Why does this matter beyond the tech-history nerd angle? Inspection is becoming as critical as lithography itself as nodes shrink below 2nm. Catching defects at EUV scales requires tools that are genuinely next-generation, and ASML is now fielding one built on technology it got for less than most Manhattan penthouses cost. The bear case is that ASML's near-monopoly on EUV already prices in a lot of good news, and inspection is a more competitive market than lithography. The bull case is that vertical integration across lithography and inspection deepens ASML's moat in ways competitors can't easily replicate.
Meanwhile, in a completely separate corner of YouTube, Fundstrat is out here reminding everyone to stop falling in love with losing positions, Investor's Business Daily is waving the white flag on individual stock picks in favor of ETFs like QQQ during this choppy tape, and jeremiah babe is doing his thing about how a $100,000 salary somehow leaves Americans in the red. Market chaos has many narrators, but only one of them is explaining how a bankrupt Dutch startup quietly handed ASML its next competitive edge.
The best deals in semiconductor history apparently happen in bankruptcy court, which is either deeply reassuring or deeply unsettling depending on your portfolio.
BullApe's AI grades every pick against the S&P 500 - wins and misses published. See the track record →